Sell My Car Hub

Selling a totaled car: take the payout, or keep it and find a buyer

Selling a totaled car comes down to one choice: let the insurer take it as part of your payout, or keep it and sell it yourself on a salvage title. Keeping it pays only if a buyer beats the salvage value the insurer deducts. Here is that math, who buys the wreck, and where your state changes the answer.

Last updated .

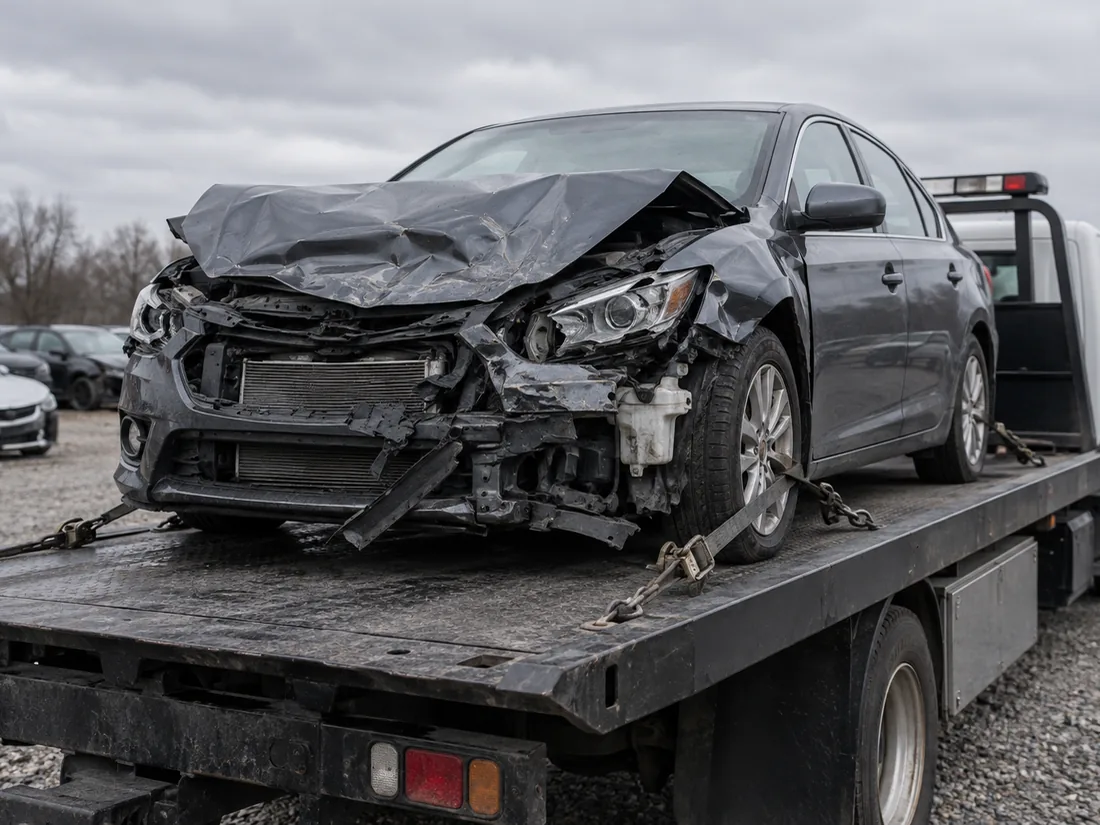
A gray sedan with its front end crushed and the hood folded up, strapped down on the bed of a flatbed tow truck.

What “totaled” means, and where your state draws the line

A car is totaled (totalled, in British spelling) when fixing it would cost about as much as it is worth, or more. As the Texas Department of Insurance puts it, if repair costs are about the same as the car's value or higher, the insurer will likely call it a total loss.

The insurer makes that call. Separately, each state sets a legal line where a damaged car has to be treated as a total loss or salvage, and the numbers are far apart. Nevada counts a car as a total loss when repairs reach 65 percent of its value. Texas calls it salvage only when repairs cost more than the car was worth just before the damage. From November 1, 2026, Oklahoma's line is 70 percent, up from 60, under a new state law. California sets no number at all. A car there is salvage when the owner or insurer considers it uneconomical to repair. Every state's rule and source is in our total-loss threshold table for all 50 states.

Even the repair bill is counted differently. Nevada leaves painting, factory-spec electronic parts and towing out of the repair cost. Texas leaves out repainting and the sales tax on repairs. So the same wreck can cross the line in one state and stay under it in the next.

One case catches people out: a stolen car that isn't found within 30 days may be labeled a total loss, and the federal title database says that label stays even if the car later turns up in perfect condition.

Your two choices: take the payout or keep the car

Once the insurer calls it a total loss, you pick one of two paths. Decide early. The Texas insurance department says that if you want to keep the car, you should tell your insurer quickly.

What changesTake the payoutKeep the car
What you getThe car's actual cash value, minus your deductibleThe same, minus the car's salvage value
Who owns the wreckThe insurerYou
TitleSigned over to the insurerA salvage or nonrepairable title in your name
What's left for you to doClear out the car and sign the paperworkGet the new title, move the car, find a buyer

If you take the payout, the car belongs to the insurer and there is nothing left for you to sell. So selling only comes up in two cases: you keep the car after the claim, or no insurer is paying at all, say because you had no collision coverage. In that second case the car is still yours, but your state may still want a salvage title. California makes that the owner's job when there is no insurance settlement.

What it costs to buy back a totaled car

You don't write a check to buy it back. The insurer just pays you less. Washington state's insurance regulator describes the salvage value as what the car is worth damaged, or what a junkyard would pay you for it. That amount comes off your settlement.

The regulator's own example, for a car worth $15,375 at a 9.8% local sales-tax rate:

LineAmount
Actual cash value$15,375.00
Sales tax at 9.8%$1,506.75
Government fees in the example$63.00
Settlement before deductions$16,944.75
Collision deductible-$500.00
Paid if the insurer takes the car$16,444.75
Salvage value-$275.00
Paid if you keep the car$16,169.75

Oregon's regulator gives a simpler version: a car worth $10,000 with a $1,000 salvage value brings a $9,000 check if you keep it. Washington also requires the insurer to add taxes, license fees and transfer fees to the cash value; ask which taxes and fees your state adds.

Here is the part that matters for a sale: the salvage value is the insurer's own estimate of what your wreck is worth, so ask for it in writing before you decide. If a buyer will pay you more than that, keeping the car and selling it yourself puts the difference, less your tow and title costs, in your pocket. If no one will, you have paid the salvage value for a car you now have to title, store and sell. To test that before you answer the insurer, get a free online offer for the wreck as it sits and compare it with the salvage figure.

Keeping it to drive instead? Get a written repair estimate first; our fix it or junk it numbers help with that call.

Who buys a totaled car

Four kinds of buyer take wrecked cars. The one pricing yours as fixed has the highest ceiling; the one pricing it as metal, the lowest.

BuyerWhat the price is built onWhat they needBest fit
Your insurerThe salvage value in your settlement; the payout sells them the wreck at that figureA signed title and an emptied carWhen nobody beats the salvage figure
Junk and salvage yardsWeight at the scrap price, plus the converter and resellable partsThe titleBurned, flooded or nonrepairable cars
Instant-offer buyers that take damaged carsThe car's condition and market data, quoted online before pickupLoan paid off, a tow timeA number to set against the insurer's figure
Rebuilders and private buyersRebuilt-title value, less repairs and the rebuilt processSalvage title first, the brand in writing, a towLight damage on a car people want

Take the payout and the insurer sells the wreck on, itself or through an auction company or pool, as the federal title database notes. Oregon's insurance regulator calls the salvage value the amount your damaged vehicle is worth to a salvage buyer: in effect, the insurer's bid.

A yard starts from metal. The U.S. Geological Survey estimates the 2025 average price of No. 1 heavy melting steel scrap at $319 per metric ton, about 14 cents a pound of steel scrap. A yard adds the converter and any resellable parts; more in what a junk car is worth.

Our partner Peddle says cars declared a total loss by an insurance company can still receive an offer, non-running included, and that in many states salvage or rebuilt titles may still be eligible. The offer is free with no obligation, you have a week to accept it, and the online figure is what the driver pays by check at pickup if the car matches your description; towing is free and the sale usually takes a few days. For Peddle, any loan must be paid in full first. To set a number against the salvage figure, see what an instant-offer buyer would pay.

A rebuilder prices the car fixed, then subtracts repairs and the rebuilt process: in Texas, the state fees listed further down plus safety and anti-theft inspections. Kelley Blue Book says a salvaged or reconstructed title has a permanent negative effect on a vehicle's value, so the ceiling sits below a clean car's. For a late-model car with body damage and a sound drivetrain this is the buyer with the most room, and the slowest: salvage title first, the brand in writing, and a tow, since Texas keeps a salvage car off public roads until it is rebuilt and retitled.
If the offer seems low, check it before you choose

The payout sets the math for both paths, so check it first. The insurance regulators in Texas, Washington and Oregon give these practical steps:

If you still owe money on the car

A loan changes who gets a say. Oregon's regulator notes the check will probably be made out to both you and the lender, and that the lender may not let you keep the damaged car. Ask your lender before you tell the insurer you want it.

A leased car is different: it belongs to the leasing company, which holds the title (Nebraska's DMV, for example, issues it in the lessor's name), so the wreck isn't yours to keep or sell. In a New York regulator's opinion on a totaled leased car, the lessor was the policy's loss payee, and the policy's terms decided who got the payout, so call the leasing company before you answer the insurer. Peddle needs all liens and loans paid in full before it buys, and a leased car belongs to the leasing company until you buy it out (see selling a leased car).

If the payout is less than your loan balance, you still owe the difference. GAP coverage is meant for exactly this. The CFPB describes it as covering the gap between what you owe and what insurance pays when a car is stolen or totaled. Check your purchase paperwork, because it is often rolled into the loan.

Look in the same paperwork for other add-ons, such as an extended warranty or service contract. The CFPB says optional add-ons can be cancelled during the loan, and that you may be owed a refund if you sell, refinance or pay the loan off early. If the insurance money pays the loan off, ask each provider whether you are owed one. For payoff quotes and lien releases, see selling a car that still has a loan.

The salvage title after a total loss

Keep the car and its title changes too. Texas, California and Oregon all make the insurer tell the state about the total loss; here is what the owner then has to do in two of them:

The brand doesn't wear off. The Justice Department's title database says a state brand becomes a permanent part of the car's record, and it already holds about 20 million salvage or total-loss records. Moving the car to another state won't clean it.

To fix the car and drive it, you retitle it as rebuilt first; in Texas that costs a $65 rebuilt fee plus a $28 or $33 title application fee, plus registration. What a rebuilt inspection checks, and what the brand does to the price, is covered in selling a salvage or rebuilt title car. Deadlines, forms and who files what differ by state, so start from your state page. Many of the title forms are explained box by box in our DMV forms library.

Selling the car once it's yours

With the salvage title in your name, you can sell, though the Texas insurance department warns that a salvage title can make a car harder to insure or sell. The four kinds of buyer described above price it differently, so collect more than one number.

  1. Get the title in your name first. Texas requires the salvage or nonrepairable title before any sale, and other states have their own deadlines.
  2. Plan for a tow. In Texas a salvage car can't be driven on public roads until it's rebuilt, retitled and registered. Check your state's rule before anyone tries to drive it.
  3. Tell buyers about the brand up front, in writing. Serious buyers will check the VIN anyway; here is which history checks are free.
  4. Test offers against the salvage value; the insurer's figure is your reference point. For how offers on damaged cars are built, see what a junk car is worth.
  5. Close it out. Sign the title over, keep a bill of sale, and file any notice your state requires. Our guide to release of liability after selling lists the state rules.

Where the law keeps a salvage car off the road, the buyer has to bring the truck. Sell through us and a carrier loads the car where it's parked, running or not, and the tow costs you nothing.

Which big buyers take a salvage or rebuilt title

If you kept the car after a total loss, this is what the national buyers publish about branded titles.

What each big buyer’s own pages say about a salvage or rebuilt title, as of 25 October 2026.
BuyerTakes it?Their rule
AutoNationnot statedFor a salvage or rebuilt title: Neither its sell page nor its FAQ page mentions salvage or rebuilt titles. Their page
Autotradercase-by-caseFor a salvage or rebuilt title: Autotrader won't list a salvage-branded car declared a total loss; its pages don't mention rebuilt titles. Their page
Carfaxnot statedFor a salvage or rebuilt title: Sell My Car pages don't say; the Carfax value counts title brands and the dealer decides. Their page
CarGurusdepends on the dealerFor a salvage or rebuilt title: Branded titles head CarGurus’ list of reasons for no offer. Their page
CarMaxnot statedFor a salvage or rebuilt title: CarMax's pages don't say whether it buys salvage or rebuilt cars; they say it never sells one with salvage history and sells cars that miss its standards to dealers at its auctions. Their page
Carvananot statedFor a salvage or rebuilt title: None of Carvana's selling help articles, its sell page or its terms mentions salvage or rebuilt titles; its general rule still requires a car it can safely drive. Their page
Drivewaycase-by-caseFor a salvage or rebuilt title: Its pages don't name salvage or rebuilt titles; its list of cars it 'may not purchase' includes 'major damage history or title issues'. Their page
Edmundsnot statedFor a salvage or rebuilt title: Edmunds will not price salvage or branded-title cars, and its pages don’t say how CarMax’s offer treats them beyond a vehicle history check. Their page
Kelley Blue BooknoFor a salvage or rebuilt title: KBB's program terms exclude reconstructed or salvage vehicles from both the Instant Cash Offer and Sell to Kelley. Their page
TrueCarnot statedFor a salvage or rebuilt title: TrueCar's archived pages don't mention salvage or rebuilt titles; the dealer decides. Their page

After the settlement: your state's title steps

Once the insurer has settled, selling what is left runs through your state's title office. Each state page lists its signing, plate and after-sale steps.

Common questions

What people ask about this

Can you keep a totaled car from insurance?

You can ask to. Tell the insurer quickly, as the Texas insurance department advises. It pays you the settlement minus the car's salvage value, and the car stays with you. In Texas it then needs a salvage or nonrepairable title. If you still have a loan, the lender may not allow it, so ask the lender first.

Do I need a salvage title before I can sell?

In Texas and California, yes, once an insurer has paid on the car and you keep it. Texas requires the owner to apply for a salvage or nonrepairable title before selling. California gives you 10 days from the settlement to apply for a salvage certificate. Check your own state's rule before you list the car.

Is keeping the car worth it if I only plan to sell it?

Only if a buyer will pay you more than the salvage value the insurer takes off your check. In Washington's regulator example that deduction was $275; in Oregon's it was $1,000. Get the insurer's figure and at least one real offer before you choose.

Can I drive a car with a salvage title?

Not in Texas. There the registration stops being valid, and the car can't be driven on public roads until it is rebuilt, retitled and registered again. A nonrepairable car can never go back on the road there. Check your own state's rule and plan on a tow to the buyer.

What if I owe more on the loan than the insurer pays?

The difference is still yours to pay unless you have GAP coverage, which is meant to cover the gap between the loan balance and the insurance payout on a stolen or totaled car. Check your purchase paperwork for GAP and for other add-ons you may be able to cancel for a refund.

My stolen car was found after the insurer paid. Is it still a total loss?

On the record, yes. The federal title database notes that a total-loss label on a stolen car is not removed when the car is recovered, even in perfect condition. The insurer, or an auction it uses, may sell the car, so ask the insurer whether you can buy it back.

On video

The short version, on video

Every line in it is a sentence from this page.

Transcript

Selling a totaled car: take the payout, or keep it and find a buyer Selling a totaled car comes down to one choice: let the insurer take it as part of your payout, or keep it and sell it yourself on a salvage title. Keeping it pays only if a buyer beats the salvage value the insurer deducts. Once the insurer calls it a total loss, you pick one of two paths. If you take the payout, the car belongs to the insurer and there is nothing left for you to sell. You don't write a check to buy it back. The insurer just pays you less. Four kinds of buyer take wrecked cars. The one pricing yours as fixed has the highest ceiling; the one pricing it as metal, the lowest. A loan changes who gets a say. Ask your lender before you tell the insurer you want it. Get the title in your name first. The four kinds of buyer described above price it differently, so collect more than one number. Once the insurer has settled, selling what is left runs through your state's title office.

Rather just sell the car?

Get My Instant Offer → Online · free · no obligation

Or send the details — we'll come to you

Kept the wreck after the claim, or had no coverage to claim on? Send the year, make and mileage, plus the insurer's salvage figure if you have it, and we'll call with a number to set beside the insurer's.

or call/text (877) 405-1808